Swiss VAT methods compared: effective, net tax rate, flat tax rate
Three ways to settle VAT with the ESTV: who may use which method, which limits apply and what the choice means for your bookkeeping.
Contents
If you are liable for VAT, you settle with the ESTV under one of three methods. Which ones are open to you depends on turnover, tax burden and legal form — and on how much effort you want to put into bookkeeping. The basics on liability and rates are in Swiss VAT (MWST) explained.
1. Effective method
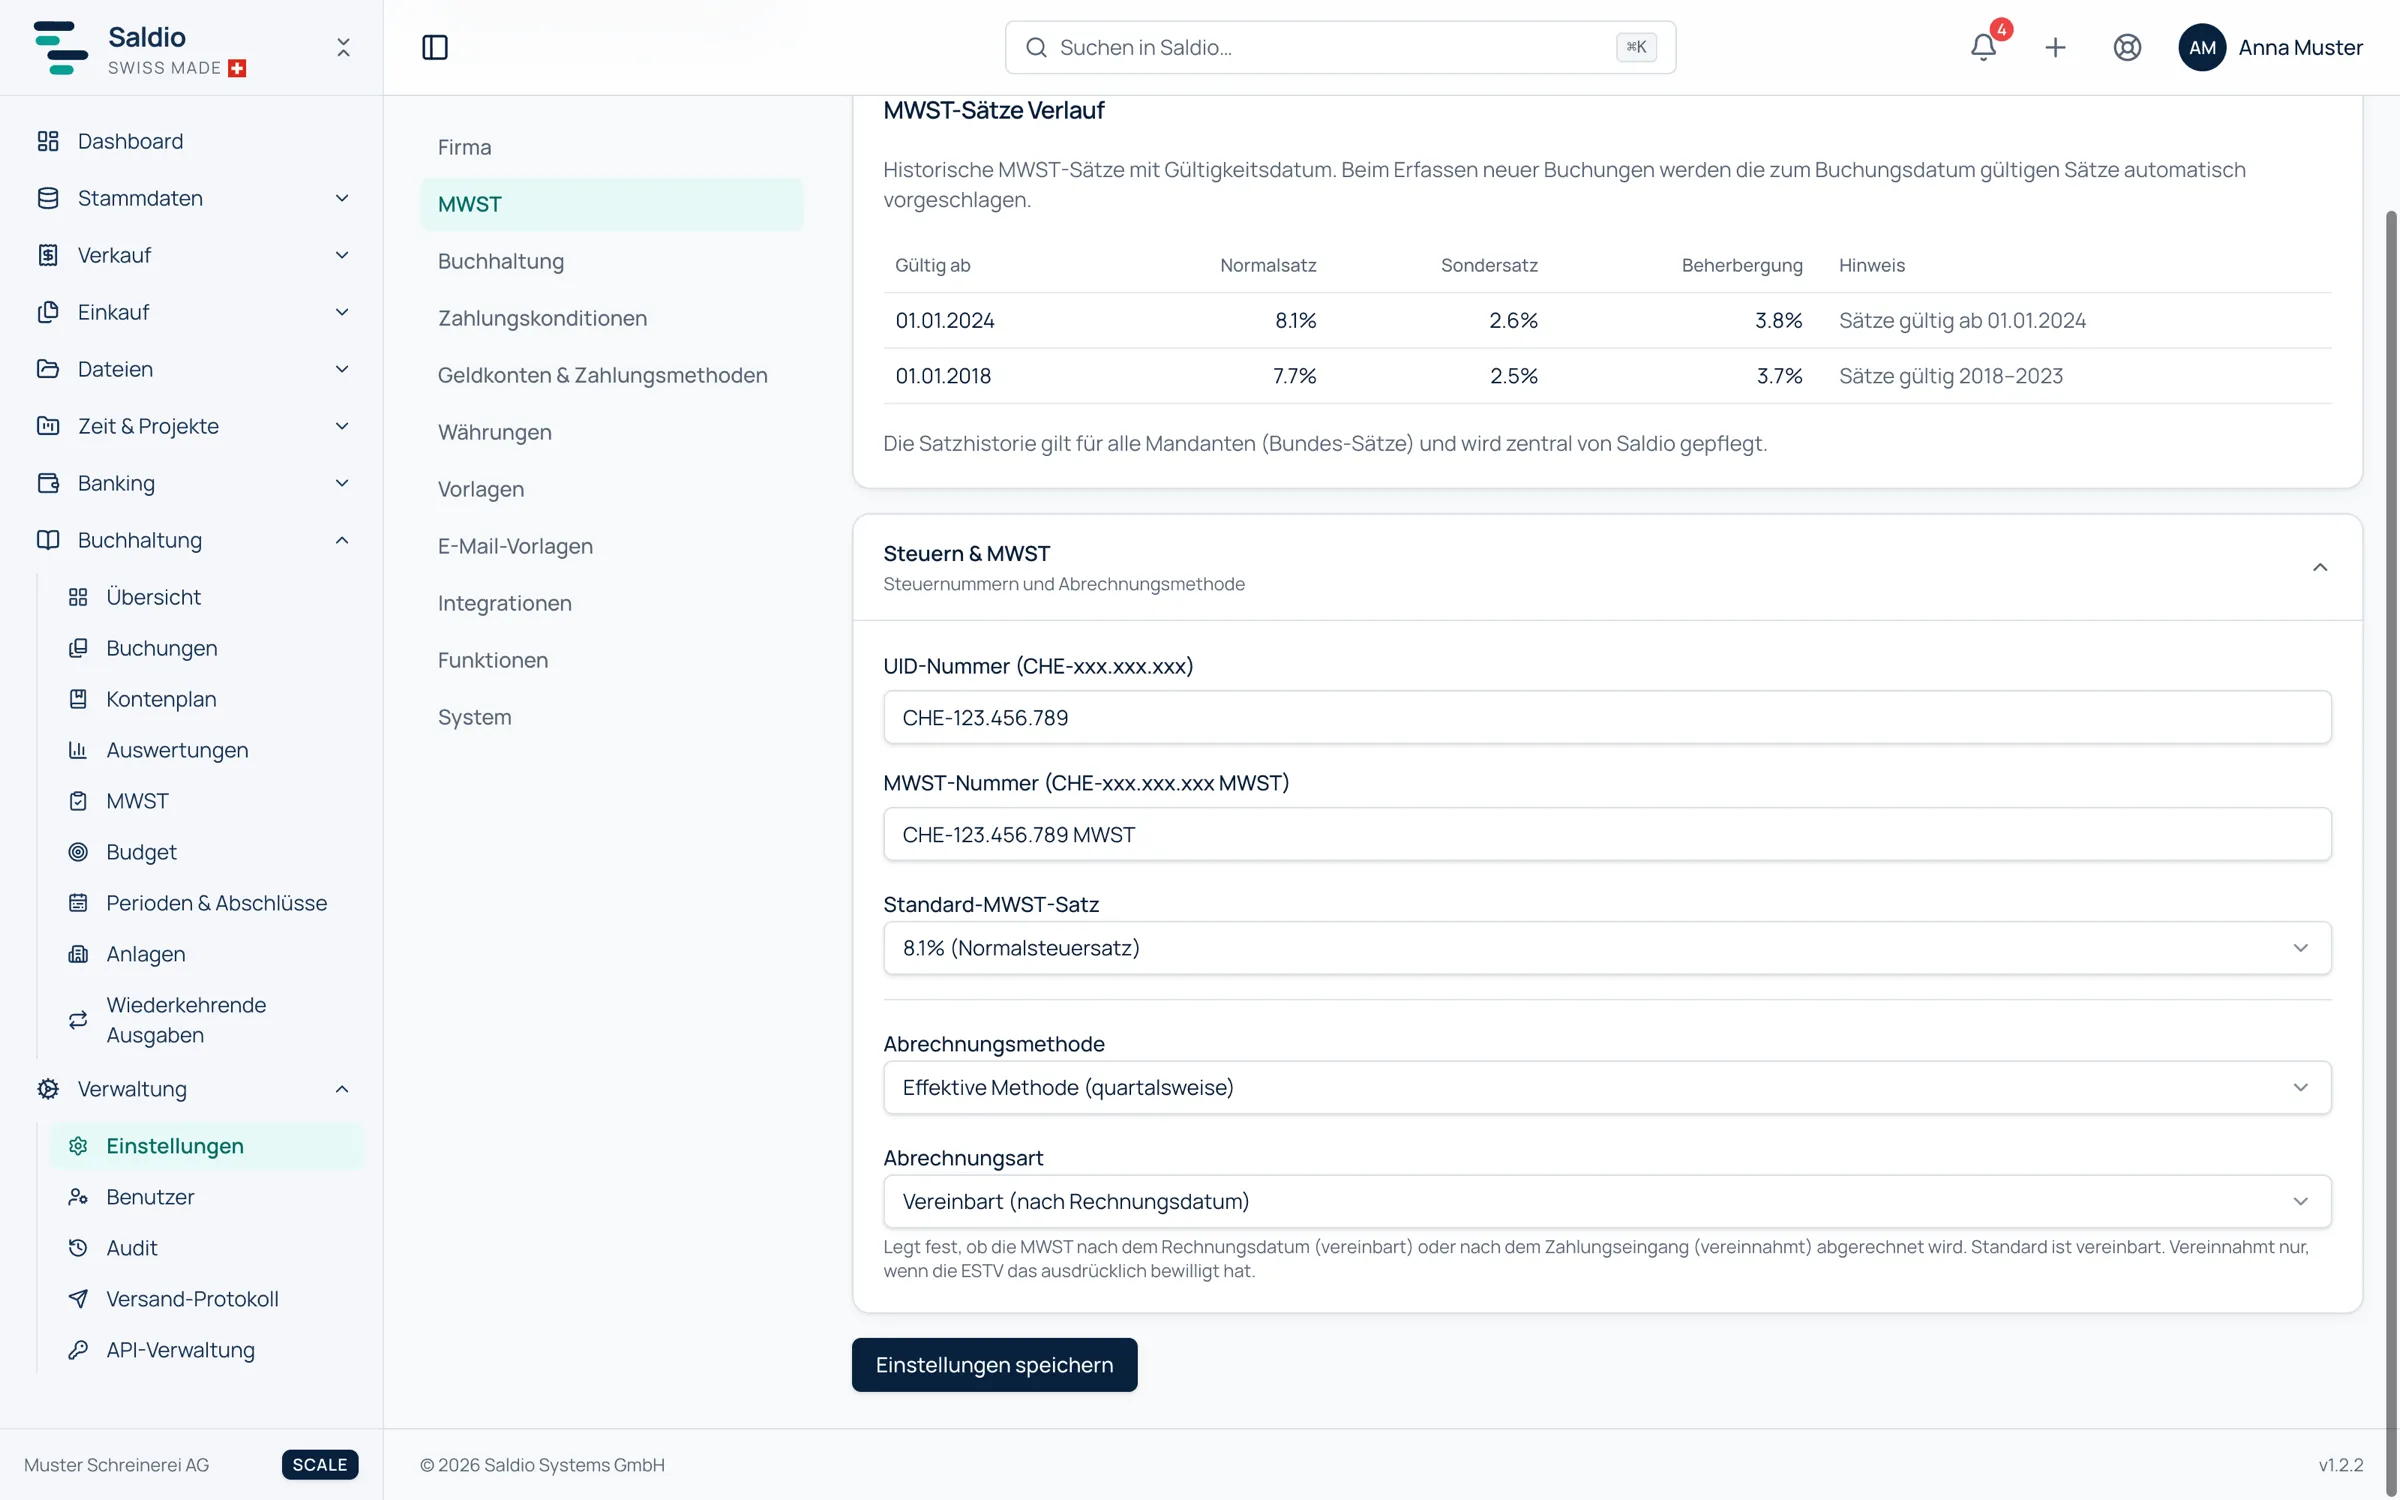
The effective method is the default. You declare turnover per tax rate (8.1 %, 2.6 %, 3.8 %) and the tax due on it. From that you deduct the input tax actually paid on materials, services and investments.
What you owe is therefore output tax minus input tax. It is precise, but it requires every document to be recorded with the correct rate and the correct input tax. Returns are filed quarterly on Form 100.
2. Net tax rate method (Saldosteuersatz)
Under the net tax rate method, turnover including VAT is multiplied by an industry-specific rate approved by the ESTV. The net tax rate already reflects the industry’s average input tax; there is no separate input tax deduction.
Requirements:
- turnover from taxable supplies of at most CHF 5,024,000 per year, including VAT
- tax, calculated with the applicable net tax rates, of at most CHF 108,000 per year
Returns are filed half-yearly. Since 2025, businesses with several activities can apply more than two net tax rates; what counts is whether an activity accounts for more than 10 % of taxable turnover.
Important in practice: invoices still show the statutory rate, for example 8.1 % — not the net tax rate. Your customers notice nothing of the method.
The method saves effort because input tax no longer has to be recorded document by document. It can cost more, though: if you have large investments or above-average input tax, you pay more at the flat rate than you would under the effective method. Switching between methods is subject to time limits and triggers input tax corrections; the details are set out in the ESTV’s VAT Info 12.
3. Flat tax rate method (Pauschalsteuersatz)
The flat tax rate method works much like the net tax rate method but is only open to a specific group: public bodies and related institutions such as private schools, hospitals or public transport companies, as well as associations and foundations. They may settle at flat rates regardless of their turnover, but the net tax rate method is not available to them. Returns are usually filed quarterly.
Which method fits?
| Method | Effort | Period | Suited for |
|---|---|---|---|
| Effective | higher | quarter | businesses with high input tax or large investments; everyone above the net tax rate limits |
| Net tax rate | lower | half-year | SMEs up to CHF 5,024,000 turnover and CHF 108,000 tax |
| Flat tax rate | lower | quarter | public bodies, associations, foundations |
Independently of the method there is a second choice: accounting on agreed consideration (by invoice date, the default) or on collected consideration (by payment receipt, only with approval).
Sources
- ESTV: Net tax rates and flat tax rates (German) — requirements, limits and periods for both methods.
- ESTV: Net tax rate method from 2025 (German) — changes since 1 January 2025, including more than two net tax rates.
- ESTV: VAT Info 12 Net tax rates — ESTV practice, including switching methods.
- Federal Act on Value Added Tax (VAT Act, SR 641.20) (German) — legal text on Fedlex.